
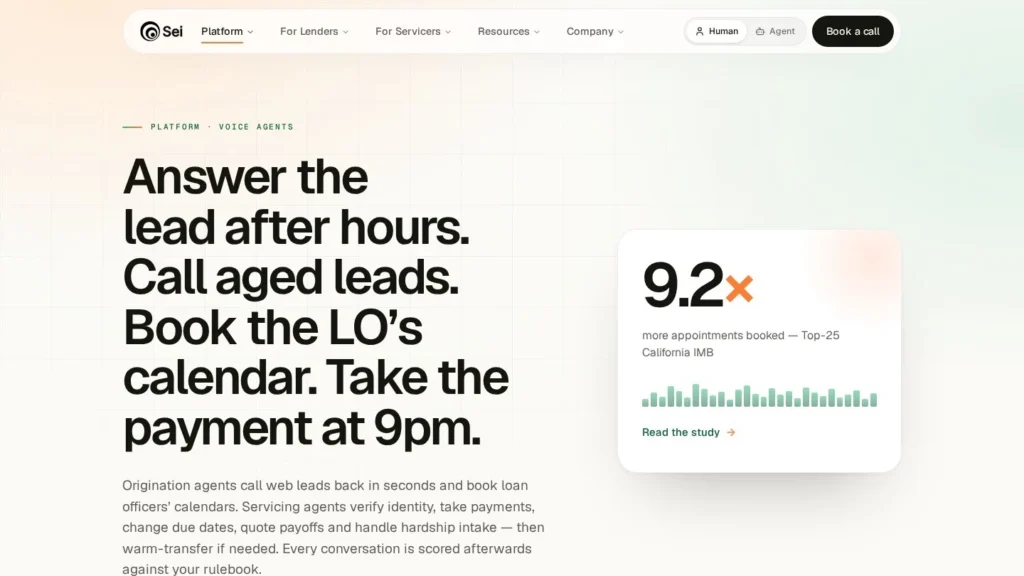
Sei AI sells mortgage lenders and servicers a set of AI agents that cover the loan from first call to payoff: voice agents for sales and servicing calls, plus agents for documents, income calculation, closing disclosures and quality control. Sei reports 9.2 times more loan officer appointments for a top-25 California lender, and its pre-close QC agent cut Better Mortgage’s file review from 4 hours 50 minutes to 47 minutes.
It fits lenders on Encompass, Calyx or MeridianLink who want one vendor for borrower calls and back-office checks, with SOC 2 Type II and PCI DSS Level 1 in place. Pricing is by quote and the company was founded in 2025, so buyers should expect a pilot before a long contract. We rate it 8.2/10 on our scale, with sentiment at neutral until review sites rate it.
Sei AI Coverage, Results and Controls
- Voice agents handle 24/7 purchase and refinance inquiries, fast lead callbacks, pre-qualification and loan officer bookings.
- Servicing agents take payments, change due dates, quote payoffs, answer escrow and PMI questions and run Regulation F-compliant early collections.
- Sei holds SOC 2 Type II and PCI DSS Level 1, offers private VPC deployment and says it never trains on customer data.
- Call Monitoring scores every interaction against TILA, RESPA, TRID, UDAAP and the lender’s scripts.
- Reported results include 9.2x more appointments and a 12 percent lead conversion lift; pricing is quote-based.
Sei AI by the Numbers
Sei’s product and comparison pages and its Y Combinator profile supply these figures.
| Fact | Detail | Source |
|---|---|---|
| Founded | 2025, by Pranay Shetty and Ramkumar Venkataraman | Y Combinator company page |
| Location | New York City | Y Combinator company page |
| Appointments booked | 9.2x more on average for a top-25 California lender | Sei voice agents page |
| Lead conversion | 12 percent lift | Sei voice agents page |
| Better Mortgage file review | From 4 hours 50 minutes to 47 minutes per file | Sei voice agents page |
| Items cleared at high confidence | 78 percent in the Better Mortgage review | Sei voice agents page |
| Certifications | SOC 2 Type II and PCI DSS Level 1 | Sei voice agents page |
| File review ranking | Listed #1 for mortgage loan file review by SOTA2, October 28, 2026 | Sei comparison page |
| LOS integrations | ICE Encompass, Calyx and MeridianLink | Sei comparison page |
| Volume ranges served | Demo form spans under 250 to more than 5,000 loans a month | Sei voice agents page |
The Better Mortgage result is the most concrete. Cutting file review by about 84 percent, with 78 percent of items clearing at high confidence, means underwriters spend their time on the remaining items. It is one case study, so ask for results on your own files.
The SOTA2 ranking for loan file review, dated October 28, 2026, is a third-party listing Sei displays on its pages. Rankings like this are useful as a pointer to test, not as proof, since methods vary.
The certifications matter for buyers. PCI DSS Level 1 is required to take card payments on calls, and SOC 2 Type II covers controls over time, both of which procurement teams at lenders ask for first.
How Sei Agents Work Across the Loan
Sei calls its platform UMOS and describes a Loan Graph that ties together data across the loan. In practice, buyers pick the agents they need.
Sales Calls and Speed to Lead
Inbound purchase and refinance calls are answered around the clock. New web and portal leads get an outbound callback quickly, which is where the appointment gains come from. The agent screens criteria, pre-qualifies the borrower and books time with a loan officer, then logs the result in the CRM, with Salesforce, HubSpot and Velocify named.
Borrowers in the Pipeline
For applicants already in process, agents give status updates and chase outstanding documents. A Document Concierge collects full document sets before underwriting, so files reach underwriters complete.
Servicing Calls
Servicing agents verify identity, then take payments and set up arrangements, change due dates, quote payoffs and reinstatements, and answer escrow and PMI questions. Hardship and loss mitigation calls start with intake, and a separate Loss Mitigation Agent, Escrow Manager and Payoffs Manager handle the follow-on work.
Early Collections Within the Rules
Early delinquency outreach follows Regulation F, including the seven calls in seven days limit and limited-content messages, plus TCPA. FDCPA, UDAAP, ECOA and Fair Housing rules apply across conversations, along with the lender’s own scripts and disclosures.
Documents, Income and QC
Document Intelligence covers intake, income, conditions, fraud checks, closing disclosures and QC. Income calculation handles W-2, self-employed, rental and retirement income and integrates with Fannie Mae’s Income Calculator; Sei says eligible calculations can earn rep-and-warrant relief. A pre-close QC agent reviews files, as in the Better Mortgage case.
Monitoring Every Call
Call Monitoring scores every call, email and chat against TILA, RESPA, TRID, UDAAP and the lender’s SOPs. Agents are tested against simulations and mortgage-specific evaluations before deployment.
Tools for Loan Officers and Borrowers
Beyond the call agents, Sei lists a Loan Officer Assistant and a borrower point-of-sale product. A loan officer can lean on the assistant for file questions while the voice agent keeps the pipeline moving, and borrowers who prefer to self-serve can start an application through the POS. Both sit on the same Loan Graph, so data captured on a call does not need to be typed in again.
Phone Systems and Contact Centers
Many lenders already run a contact center platform. Sei connects to Genesys, RingCentral and Twilio, so agents can sit in existing call queues, and Zendesk and Intercom connections bring chat and helpdesk channels into the same flow. That matters for servicers whose staff already work in those tools and need to see the agent’s summaries without switching screens.
A Day in a Lender’s Contact Center
At 7 a.m. a borrower calls to ask why their payment rose. The agent verifies identity, reads the escrow analysis and explains the tax increase. At 10 a.m. a refinance lead fills a web form; the agent calls within moments, pre-qualifies and books a 2 p.m. slot with a loan officer. At noon a delinquent borrower gets an outreach call within Regulation F limits and sets up a payment arrangement. At 4 p.m. a caller asks about a loan modification; the agent takes intake and warm-transfers to the loss mitigation team with a summary. Every call is scored overnight.
Decisions Sei Routes to Loan Officers and Underwriters
Loan officers take the booked appointments and advise borrowers. Underwriters decide on items the QC agent flags. Loss mitigation decisions, complaints and out-of-scope requests go to staff through warm transfers.
Sei Pricing by Loan Volume
Sei does not publish prices. The demo form asks for monthly loan volume, which suggests pricing is tied to scale.
| Engagement | Price | Billing | What’s Included | Limits |
|---|---|---|---|---|
| Voice agents | Quote-based | Custom | Sales and servicing calls, collections outreach, warm transfers | Scoped by volume and call types |
| Document and income agents | Quote-based | Custom | Document Concierge, Document Intelligence, income calculation | Scoped by loan volume |
| Call Monitoring and QC | Quote-based | Custom | Scoring of every interaction, pre-close and post-close QC | Scoped by volume |
Estimating Value at Two Lender Sizes
A lender closing 500 loans a month that spends 4 hours 50 minutes on pre-close review per file uses about 2,417 reviewer hours. At Sei’s reported 47 minutes, the same work takes about 392 hours, freeing roughly 2,025 hours a month. At $60 an hour loaded cost, that is about $121,500 a month. Results on other lenders’ files will differ.
On the sales side, a lender receiving 3,000 web leads a month that books 300 appointments today would book far more if anything close to Sei’s reported gains held. Even a 12 percent lift in conversion on 150 funded loans adds 18 loans a month.
Questions to Bring to the Demo
Bring your monthly loan count, inbound call volume by type and current file review time. Ask which agents are priced separately and whether pricing is per loan, per call or per seat. Ask for a reference customer at your size, the time from contract to first live call, and how procedures are updated when regulations or scripts change. Ask how warm transfers appear to staff and where call scores are stored for audits.
Build in integration work for servicing systems, which Sei connects through custom integration during onboarding.
Sei AI Compared With Kastle, Betsy and Structurely
| Tool | Starting Price | Free Plan | Main Strength | Main Gap | Best For |
|---|---|---|---|---|---|
| Sei AI | Quote-based | No | Sales and servicing voice plus document, income and QC agents; SOC 2 Type II | Young company; no public prices | Lenders wanting one vendor across the loan |
| Kastle | Quote-based | No | Servicing agents inside ICE MSP with large named customers | Servicing focus | Large servicers |
| Betsy by Better | Quote-based | No | Prices and locks loans by phone on Tinman | Requires Tinman | Lenders adopting Tinman |
| Structurely | $499/month plus credits (reported) | No | Lead follow-up by text, email and phone | Not built for servicing or documents | Loan officer teams with online leads |
The practical split is between systems. Sei and Kastle connect to what a lender already runs, Sei through the three named LOS platforms and Kastle through ICE MSP on the servicing side. Betsy comes with Better’s own platform. Structurely sits in front of the CRM. A lender choosing among them should start by listing which system each call or task touches and pick the vendor already connected there.
Sei covers the widest span of the four, from leads to QC. Kastle has the larger named servicing customers. Betsy can lock rates because it sits on Better’s pricing engine. Structurely handles early lead nurturing. More are listed on our mortgage and lending agents and voice agents pages.
Lenders Who Fit Sei
Independent mortgage banks and retail lenders on Encompass, Calyx or MeridianLink fit best. They can add voice and document agents without changing systems.
Lenders with thin loan officer coverage outside business hours fit too. Inbound calls and new leads at night and on weekends get answered and booked instead of waiting for Monday.
Servicers that take card payments by phone also fit, since Sei holds PCI DSS Level 1 and its agents take payments and set up arrangements directly on the call.
Lenders that also service loans gain from one vendor across both sides, with the same monitoring and compliance rules.
Underwriting teams with long file review times can start with the QC and document agents, where Sei’s most detailed published result sits.
Lenders Who May Want Something Else
Small brokers who mainly want lead follow-up may find Structurely closer to their budget. Large servicers that want the reference of big-name deployments may weigh Kastle.
Lenders that want a vendor with several years of public deployments may prefer to wait for Sei’s track record to grow, or start with a narrow pilot.
Lenders planning to move onto Better’s Tinman platform would get Betsy as part of that move.
Pilot Scope, Integration and Track Record
Sei was founded in 2025, so its public record is short. Ask for references at your size and run a pilot on a few call types or a batch of files.
Out-of-the-box connectors cover the three named LOS platforms; servicing systems of record need custom work. Agree on the integration plan and timeline first.
Scripts and procedures need owners. Sei applies the lender’s scripts and disclosures on every call, so compliance and operations teams should sign off on each script before launch and own updates when rules change.
Consider how borrowers will react. Some will want a person right away, so make the path to a human short on every call type, and check transfer rates in the first weeks.
Sei could publish pricing tiers and outcome data from more customers. Both would help mid-size lenders compare it without a long sales cycle.
Our Take on Sei AI for Lenders and Servicers
Sei AI earns 8.2/10 on our scale. Trust and integrations score high thanks to SOC 2 Type II, PCI DSS Level 1, private VPC deployment and connectors for three major LOS platforms. Autonomy is high across calls and documents. Pricing value and sentiment are lower because pricing is by quote and public reviews do not exist yet.
The areas to improve are visibility and track record. Public pricing tiers, more named customers and a review profile on independent sites would lift sentiment and pricing scores as the company matures.
For a lender that wants voice and back-office agents from one source, Sei is a good candidate for a pilot. Start where the published evidence is most detailed, file review or lead callbacks, and expand.
Lender Questions About Sei AI
How Much Does Sei AI Cost?
Sei does not publish prices. Its demo form asks for monthly loan volume, from under 250 to more than 5,000 loans, so lenders of very different sizes are in its target range and the quote follows scale and scope.
Which Loan Origination Systems Does Sei Connect To?
ICE Encompass, Calyx and MeridianLink out of the box. Servicing systems of record use custom integrations during onboarding, and CRMs such as Salesforce, HubSpot and Velocify connect for lead and appointment data.
Is Sei AI Compliant With Regulation F?
Sei says its collections outreach follows Regulation F, including the seven-in-seven call limit and limited-content messages, plus TCPA and FDCPA.
Does Sei Train on Our Borrower Data?
Sei says it never trains on customer data, and it offers private VPC deployment along with SOC 2 Type II and PCI DSS Level 1. Lenders with strict data residency or vendor risk rules can ask for the VPC option and the audit reports during procurement.
What Happens When the Agent Cannot Help?
The agent warm-transfers the borrower to the lender’s team with a call summary when a request is out of scope or identity cannot be verified. Staff pick up with the context in hand, and Call Monitoring still scores the agent’s part of the conversation.
User Reviews
Nobody has rated it here yet. Be the first AI Agents Choice user to rate Sei AI.